
Technology Service Provider
Infrastructure for regulated institutions
We build and operate payment, banking and messaging infrastructure for banks, NBFCs and licensed entities. You hold the regulatory relationship; we run the technology underneath it.
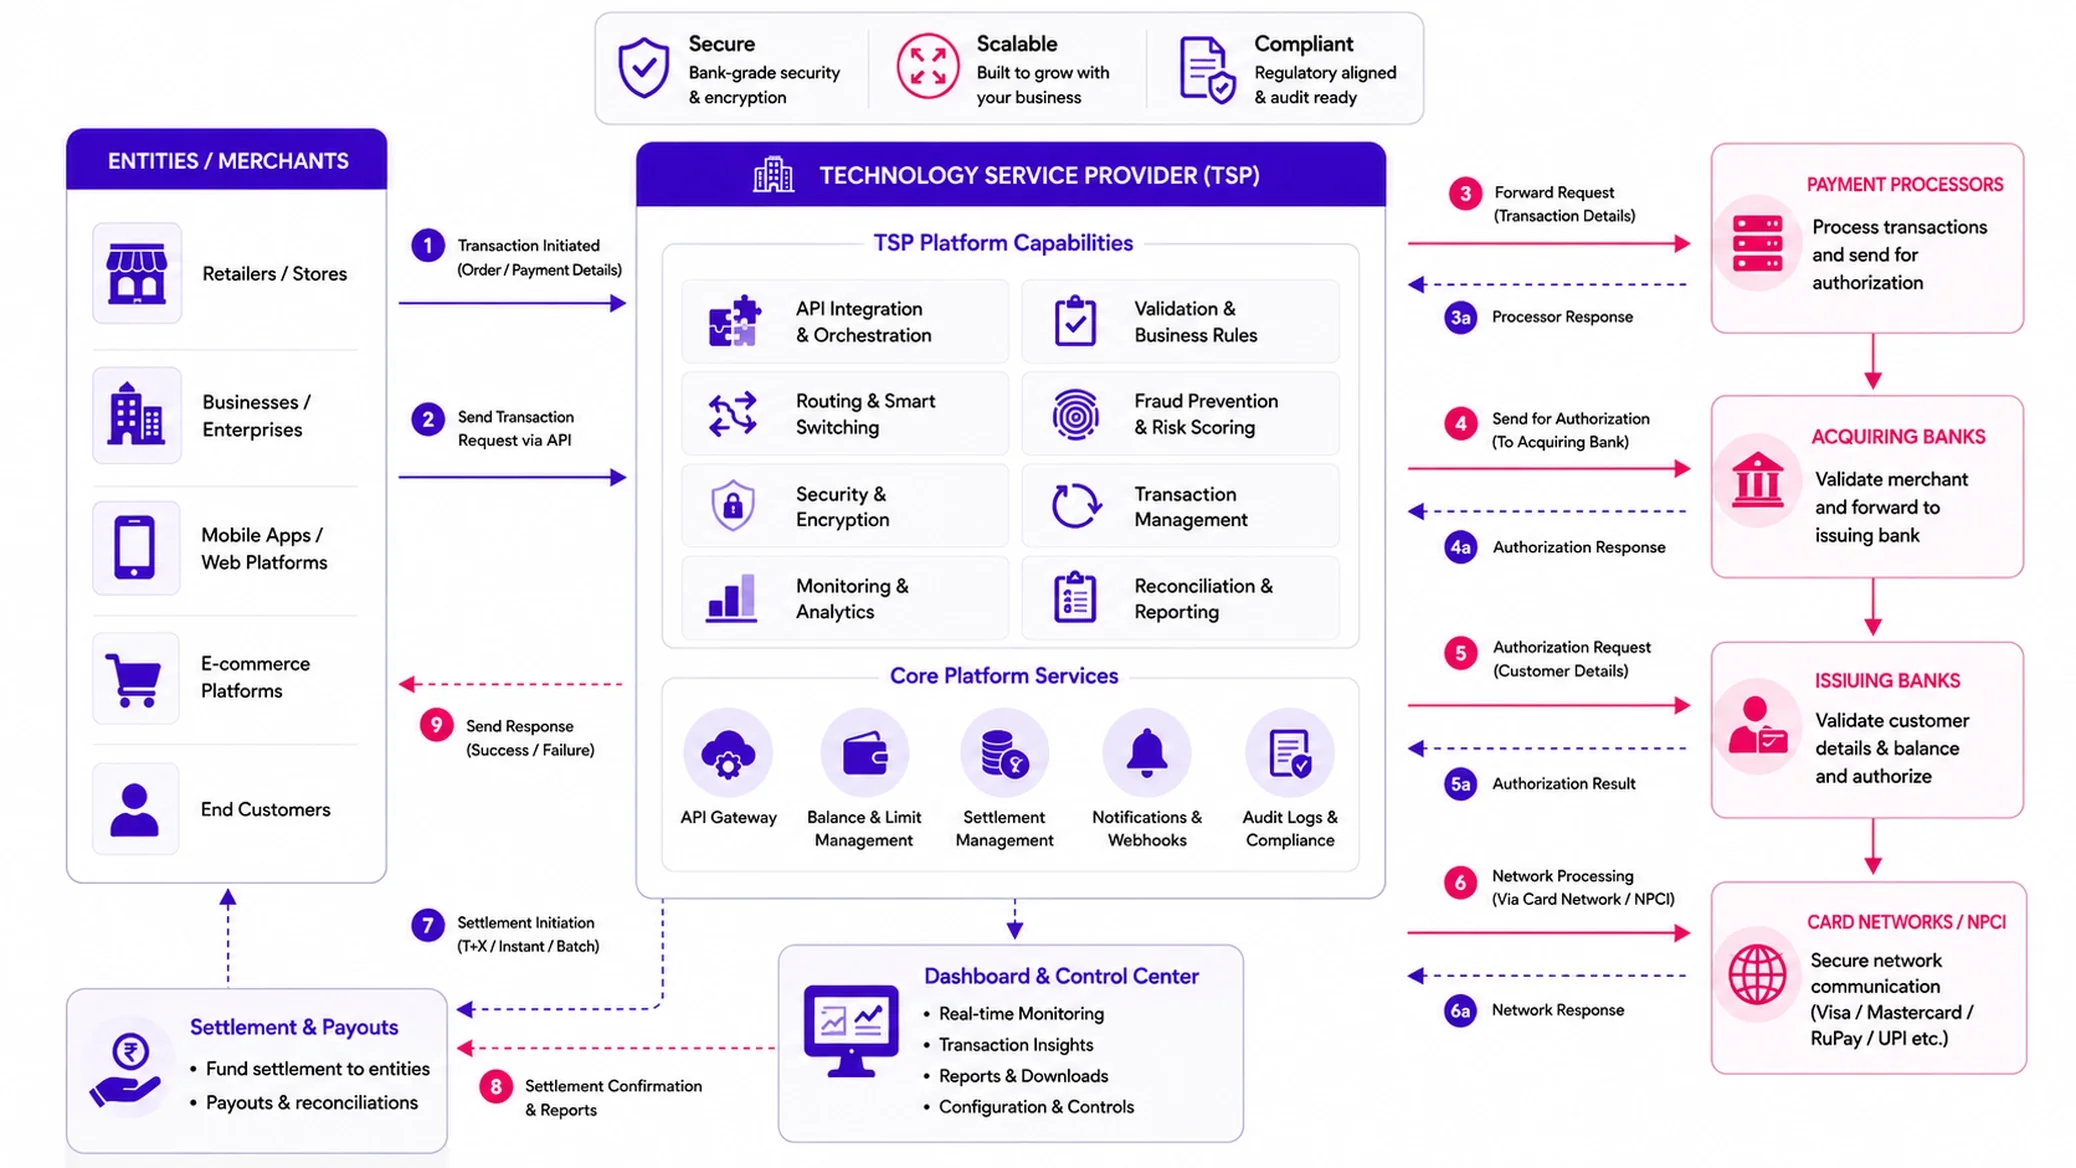
Payment Gateway
Collection infrastructure operated on your behalf.
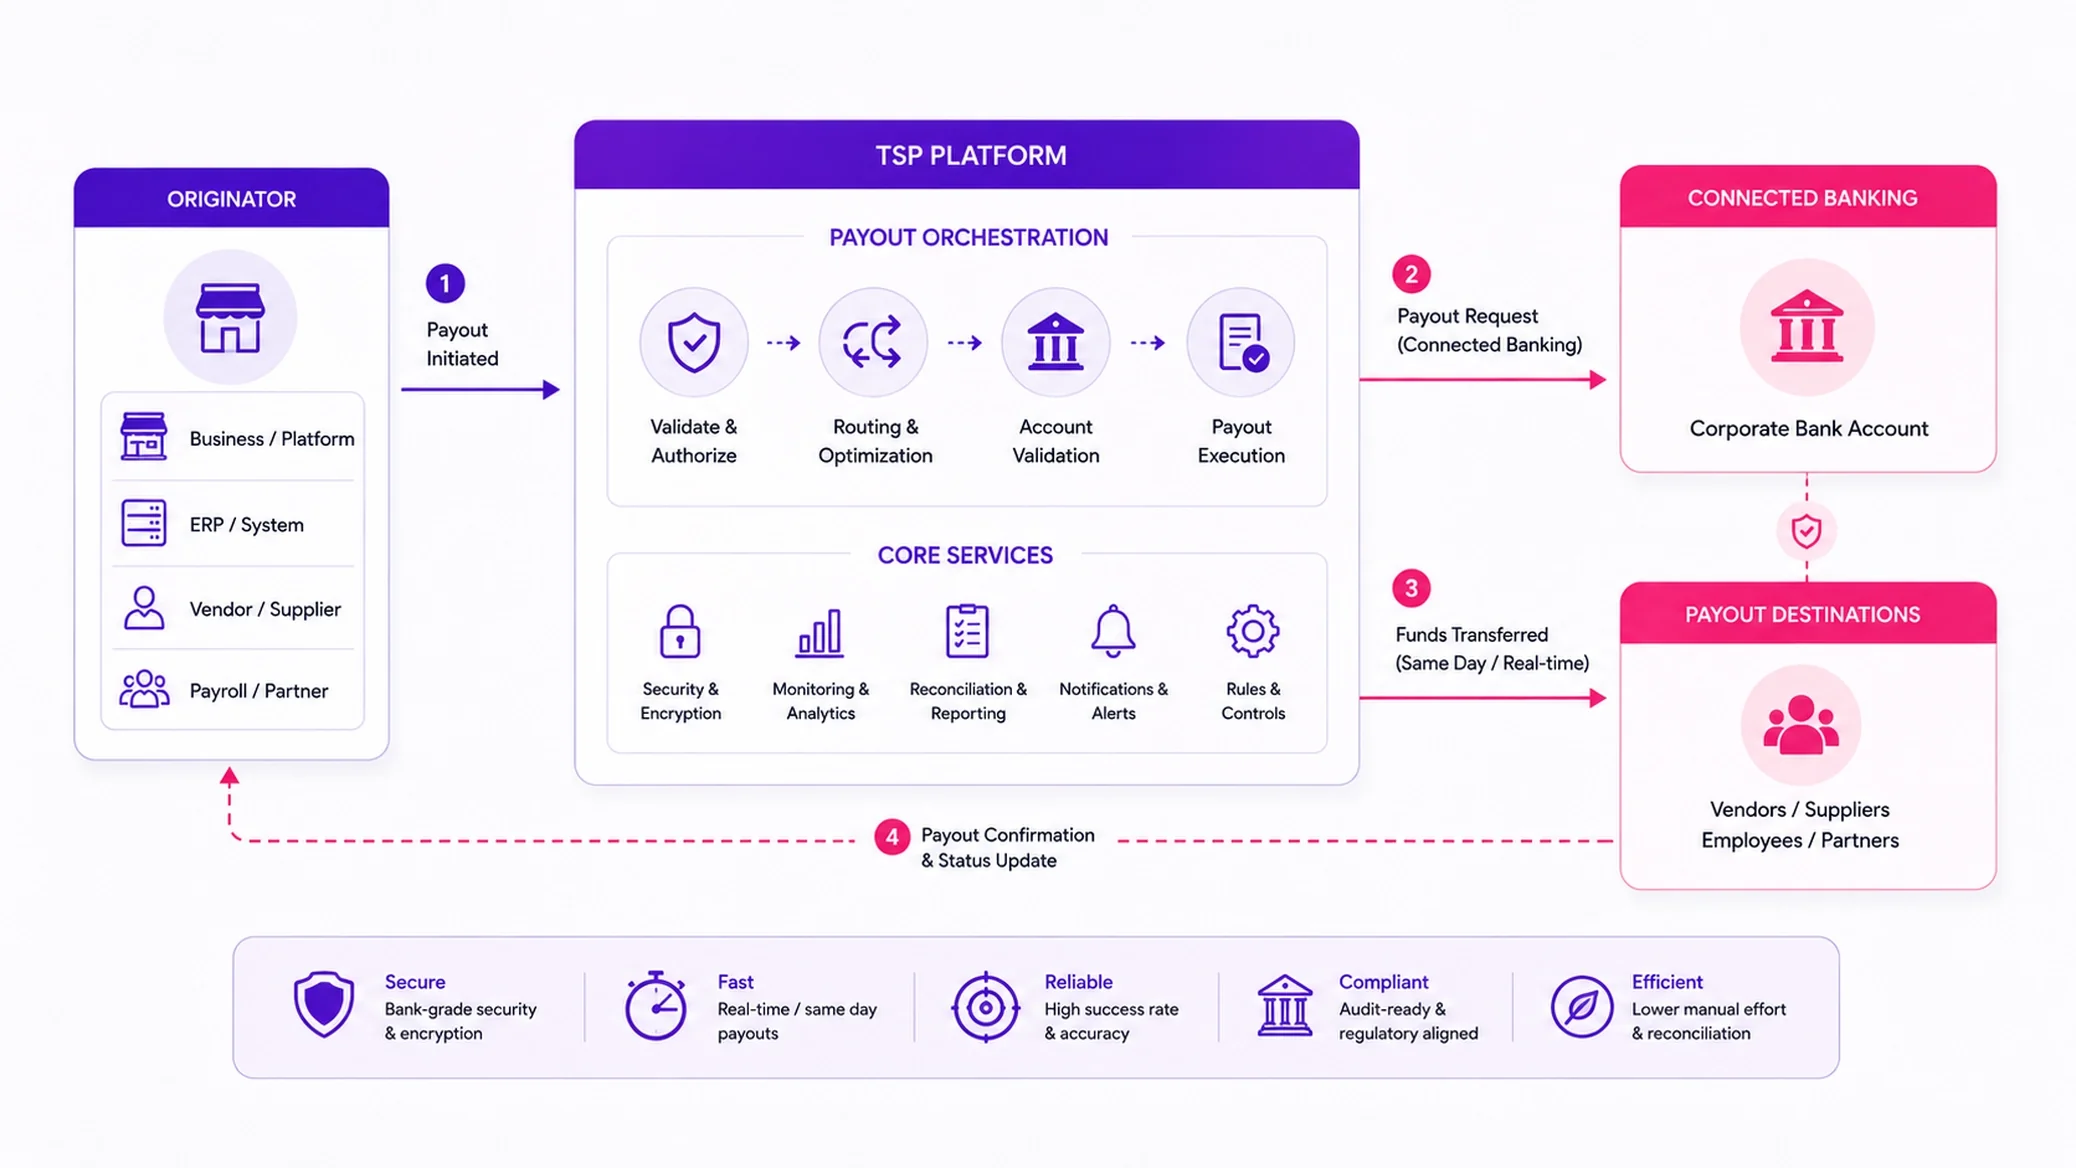
Connected Banking Payout
Payouts direct from your corporate bank account.
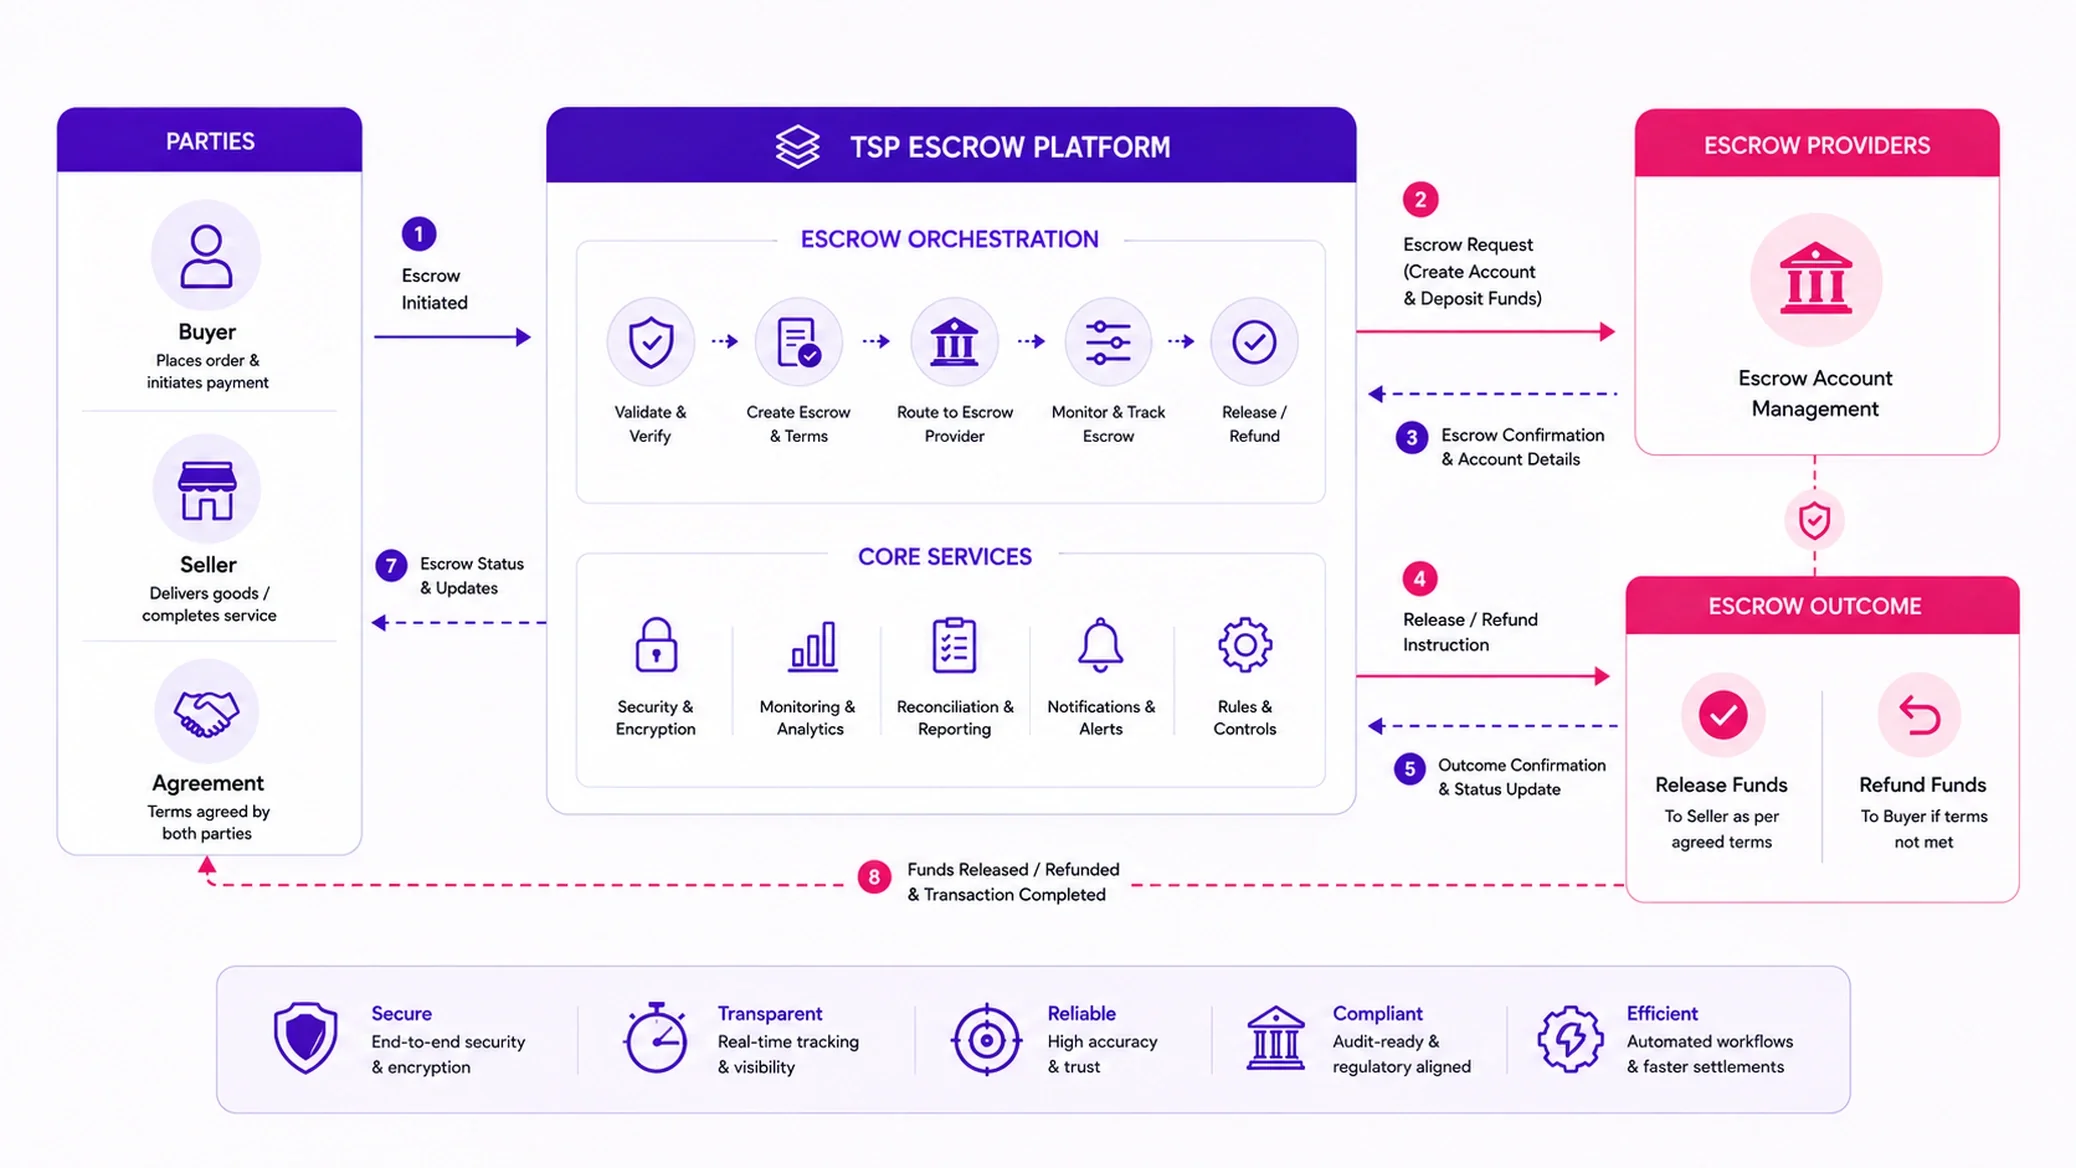
Escrow
Client money held separately, released on defined conditions.
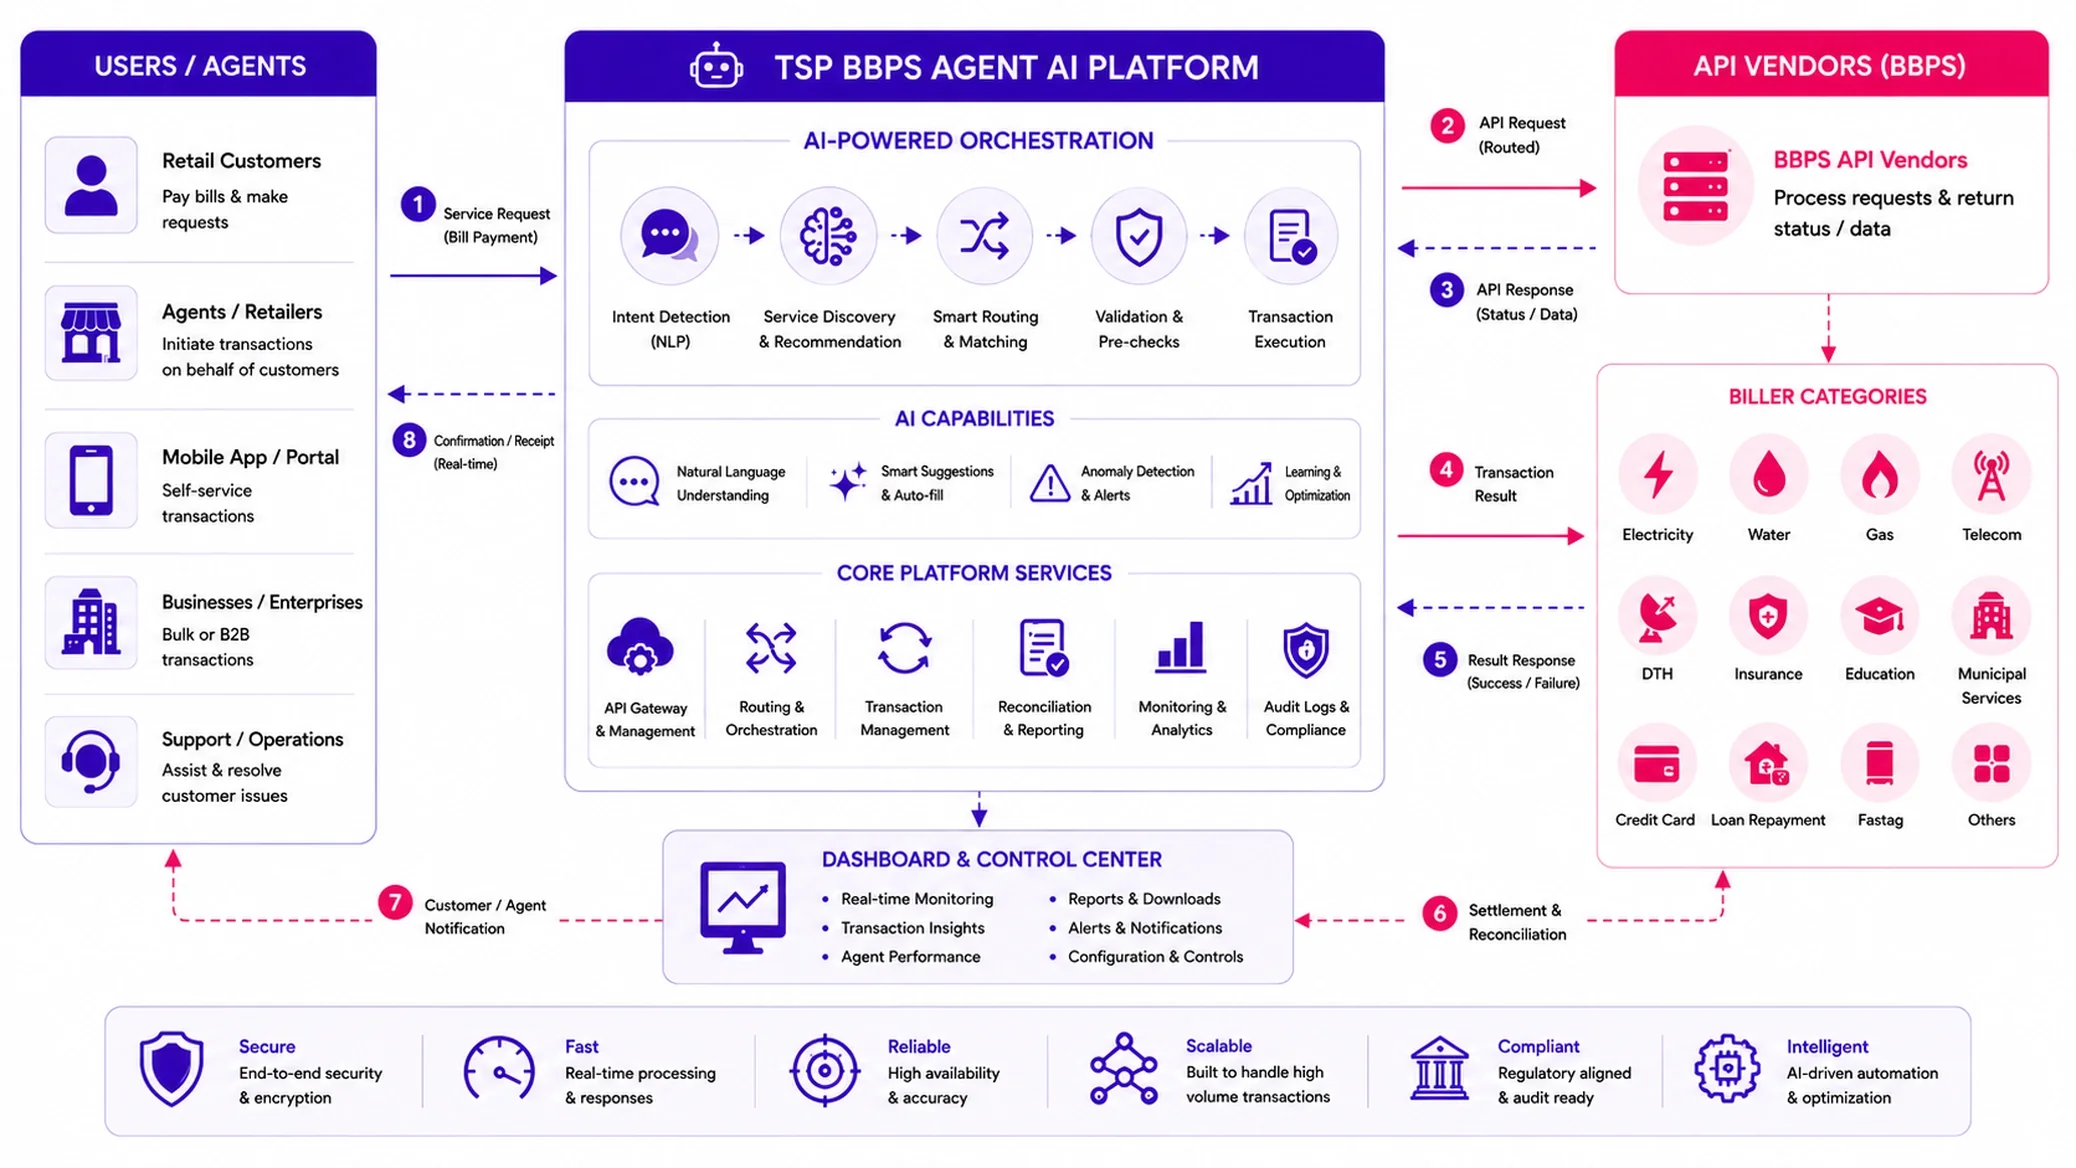
BBPS Agent AI
Assisted bill payment that resolves the biller for the customer.
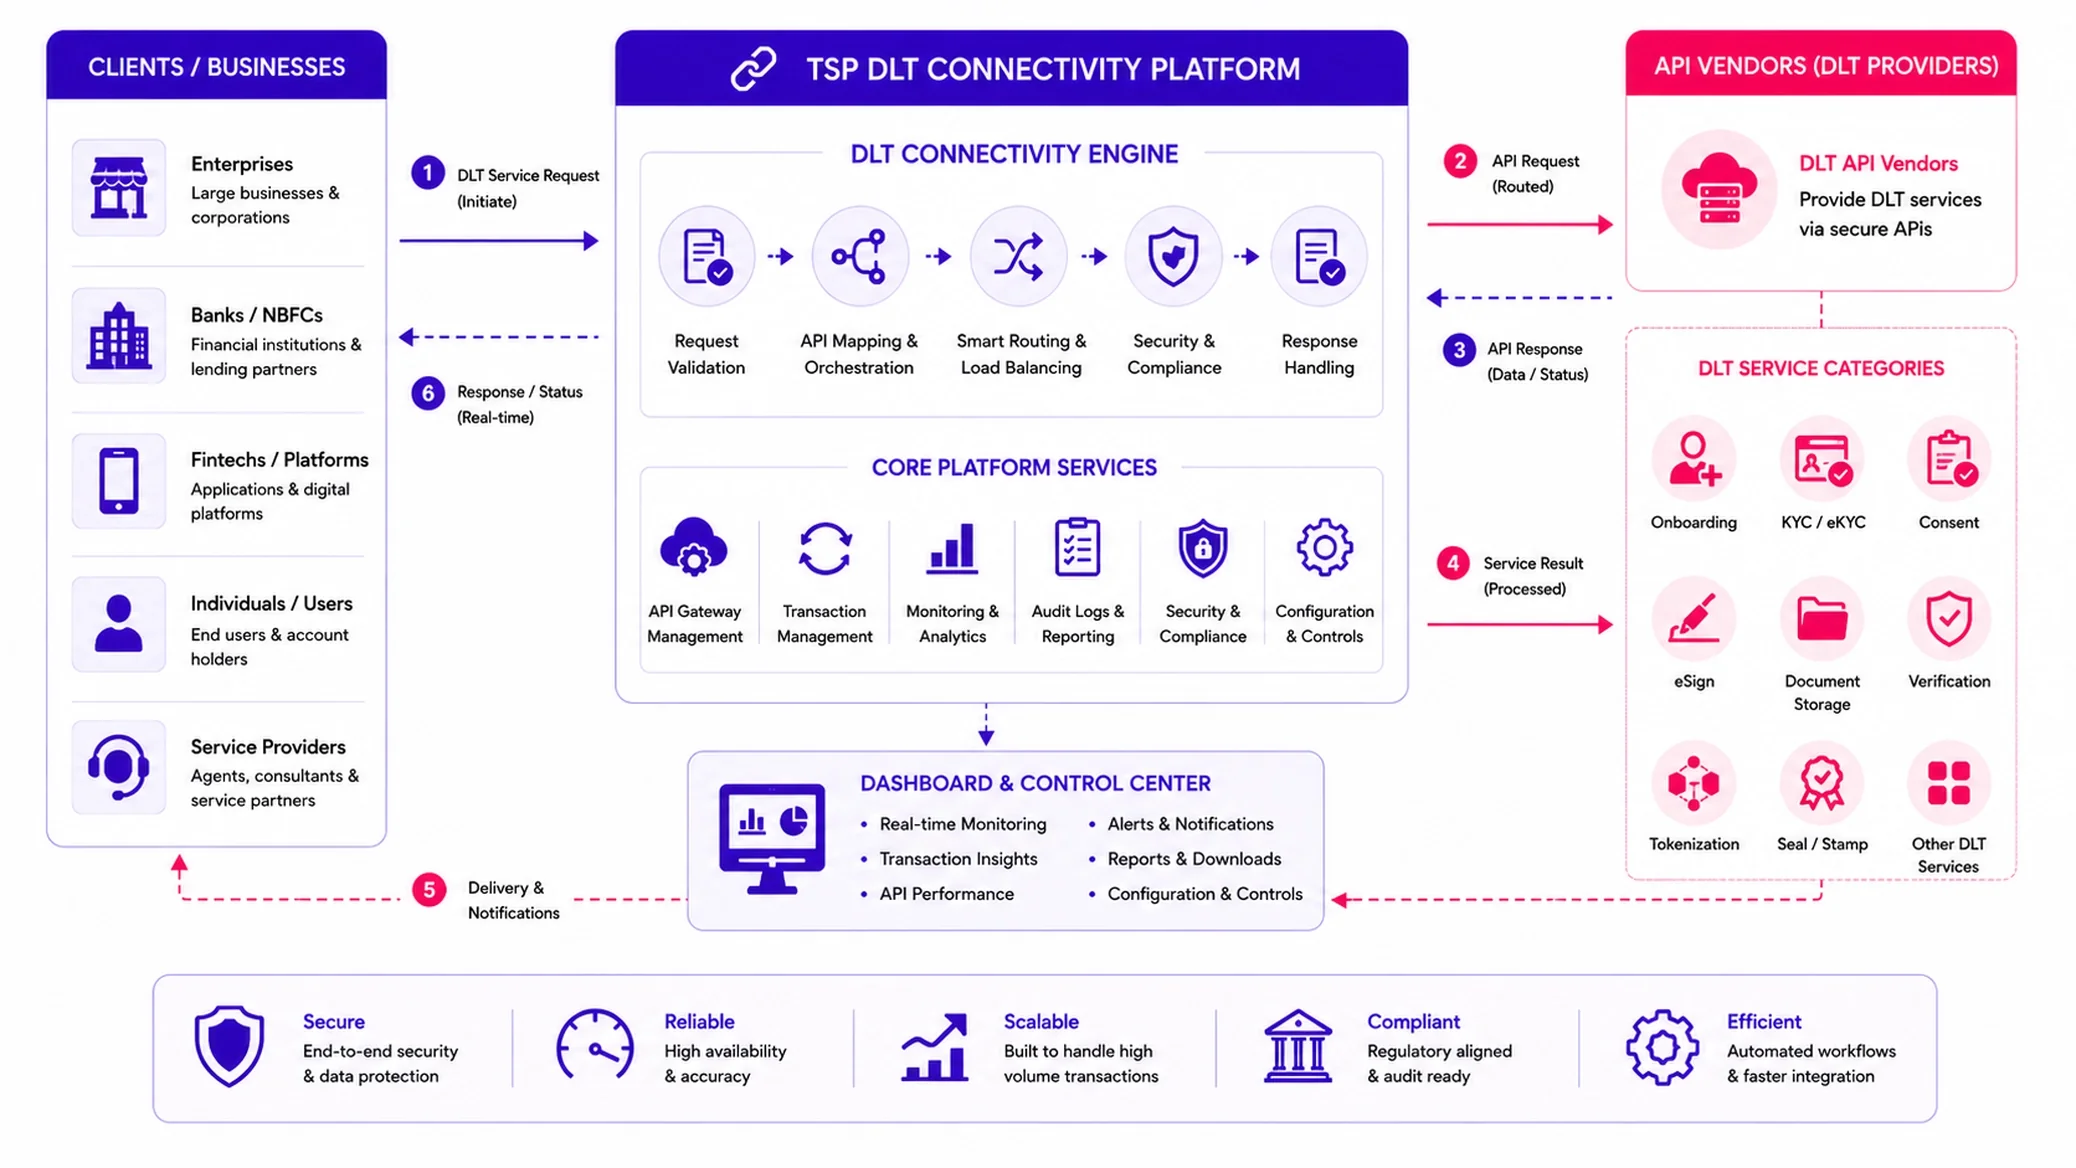
DLT Connection
Registration and template management for SMS that reaches handsets.
FAQ
Questions from institutional buyers
How is this different from the standard payout rail?
The standard rail draws from a wallet you fund in advance. Connected banking initiates from your own account, so the float stays yours and the reconciliation is against your own bank statement. It requires a supported bank relationship, which the standard rail does not.
Who controls the release of funds?
The agreed rules do, and neither party can unilaterally override them. That is the entire value of escrow: if either side could release at will, it would just be a bank account with extra steps.
What happens if it picks the wrong biller?
It does not pay on its own. The resolved biller and the fetched bill are shown for confirmation before any money moves, so a wrong resolution costs a correction rather than a misdirected payment.
Why are our messages not being delivered?
Almost always a template mismatch. Delivered content must match an approved template exactly, including variable placement, so a small copy edit that was never resubmitted silently kills delivery. Diagnosing this is most of what DLT support actually involves.